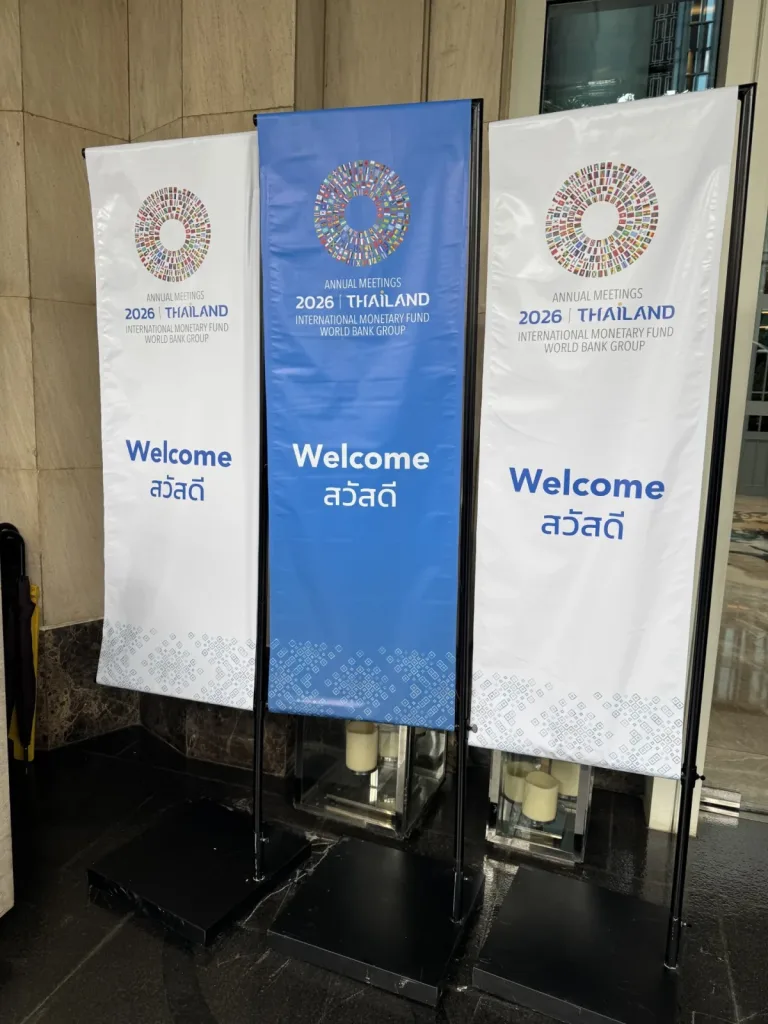
Last week, the annual meetings of the IMF and World Bank took place. As happens every three years, on this occasion they were held outside Washington – in Bangkok. The meetings had an overarching theme, which can be summarised as “Fragile Resilience”. In their recent publications, the IMF and World Bank highlighted how the global economy had been resilient in the last few years, in the face of some of the largest shocks in recent history: the trade shock initiated by the “reciprocal tariffs” announcement made by US President Donald Trump on 2 April 2025, and the oil shock deriving from the war in Iran, initiated by the US-Israeli attacks of 28 February 2026.
Countering these shocks, a number of cushions have allowed the global economy to absorb their impact. First and foremost, the AI revolution and the investment in data centres it is generating. Secondly, the fiscal space that some countries had, which allowed governments to partially offset the impact on companies and households. Thirdly, monetary policy, which could be eased to some extent by the major central banks.
But the IMF now warns that these shock absorbers have almost all been exhausted. First, doubts abound as to whether AI companies will really be able to generate the returns on their massive investments that they are currently promising. The risk is that open-weight models will eventually prevail, especially those made in China. Secondly, the level of debt and deficit reached by some of the most advanced economies, including – or especially – the US, does not allow additional fiscal easing by governments: bond vigilantes are out in force, as shown by the rise in long-term yields at the international level. Thirdly, central banks have had to focus on their primary objective of containing inflation, which was pushed above target in most countries as a result of the rise in energy prices.
The IMF has summarised all this in a sentence: “Growth has endured so far, but rising inflation and narrowing buffers demand policy action now”, and a warning, encapsulated in the IMF Managing Director’s speech: “Rebuilding Buffers Without the Luxury of Time”. We summarise all this with an expression that seems an oxymoron: “fragile resilience” – the global economy has proven resilient, but this resilience is now vulnerable to further shocks as the shock absorbers have been nearly exhausted, and so now it is fragile.
What’s the impact of all this on global economic activity and inflation? As the latest World Economic Outlook says, “global growth is projected to slow to 3.1 percent in 2026 and rebound to 3.4 percent in 2027. Global headline inflation is projected to rise notably to 4.7 percent in 2026 before easing to 4.1 percent in 2027.”
Financial markets have also shown notable resilience in the face of such repeated shocks: equity markets have reached new all-time highs over the last few years, even as long-term rates rose to levels unseen in three decades.